WInston Trails homes for sale

Showing posts with label foreclosure fraud. Show all posts

8/24/11

Is Florida the Next Non-Judicial Foreclosure State

I have heard, second hand, that this bill has been shelved. I don't know if that is accurate or permanent, so...Please forward this blog post to every Floridian that you know or share it on your Facebook page…if this gets passed, it will be devastating for tens of thousands of homeowners. It will, in essence, take away the right to challenge the banks foreclosure (fraudulent documents and all) AND includes a huge disincentive to foreclosure defense attorneys from even taking your case.

If the mortgage industry has its way, the passage of a new bill floating around Tallahassee will ensure that Floridians will be displaced from their homes without legal representation or due process.  In typical Orwellian style, this bill is entitled the Fair Foreclosure Act – it’s anything but . . .

Florida often makes the national news when it comes to foreclosures, and it’s never positive.  According to a recent 24/7 Wall Street study, three of the ten housing markets most likely to collapse in 2012 are in Florida.  Naples, Miami and Ft. Lauderdale all make the top 10, and the rest of the Sunshine State isn’t far behind.
In its preamble, the FFA actually says, “Once suit has been filed, the public interest is served by moving foreclosure cases to final resolution expeditiously in order to get real property back into the stream of commerce.”  Of course, it is this glut of foreclosed homes flooding the real estate market that has all but ensured its collapse.  REO properties typically sell far below market value, and when so many REOs exist, it drives the overall market to new lows.  The vicious cycle is complete as more homeowners suffer increased losses from a down market.

So the bill’s stated purpose is flawed right from the outset, but getting our homes back into the “stream of commerce” really isn’t the purpose of the Fair Foreclosure Act.  Its sole design is to take Floridians’ property without due process or equal protection under the law.

Florida has a proud history of whoring for the mortgage industry, and while states across the country are fighting to restore honor and integrity to our judicial system, Florida has taken a different approach.  In Florida, the Supreme Court and our elected state officials are doing what they can to ensure their benefactors . . . the banks . . . get what they want.

Remember Foreclosure Court?   It unconstitutionally employed retired senior judges to act as mortgage mercenaries – ramrodding defective foreclosures through the judicial system despite national ridicule.  I am actually shocked it fell victim to Governor Scott’s massive spending cuts.  That must have been a mistake.
Then, with the addition of Pam Bondi as our new Attorney General, the mortgage industry took firm control of our prosecutors as well.  Ms. Bondi all but killed any investigation into foreclosure fraud, and fired two assistant prosecutors who gained national attention for piecing together a massive conspiracy by the mortgage industry to defraud our state court judges in foreclosure cases.

BUT, these acts of treason pale in comparison to the Fair Foreclosure Act, which proposes to do the following:
  • Where the amount of principal and interest equals or exceeds 120% of the just value of the home, it will allow the mortgage company to foreclose without going through the judicial process.  That means no foreclosure complaint, no defense, no due process, no justice.  It will be as easy to take your home as it is to repo a car.
  • It will repeal Florida Statutes § 57.105, which awards attorney fees to homeowners who successfully defeat mortgage companies in court.  At the same time, it assesses attorney fees against a homeowner and his lawyer (in equal parts) if the mortgage company prevails.  The design here is to stop consumer lawyers from taking any more foreclosure cases by making it impossible to make money and even personally expose the lawyer to penalties.  Consumer lawyers will have no upside potential and all downside risk.
  • It will eliminate the right of a homeowner to set aside a wrongful foreclosure, even if the plaintiff committed fraud in the process of taking the home.  The ONLY recourse would be awarding money damages.  This language is to appease the title companies by retroactively ratifying all that foreclosure fraud that has taken place over the last decade.  Once the bank takes your home, you’ll never get it back, no matter what.
The typical knee-jerk response is always that these homeowners are people who “got in over their head.”  But such banking propaganda ignores the fact that 1 in 2 houses in Florida have no equity.  So, according to bankers, half of Floridians are irresponsible homebuyers. Wall Street and greedy bankers created this horrible mess, but they want no part of shared sacrifice in cleaning it up.  Middle class America didn’t cause this problem, and Middle class America shouldn’t pay for it.

We Floridians suffer from foreclosure fatigue, and the FFA will send us all over the edge.
This article comes courtesy of Chip Parker, A Jacksonville Bankruptcy Attorney. About Chip Parker, Jacksonville Bankruptcy Attorney
Chip Parker is the managing partner of the fastest growing law firm in Northeast Florida (two years running), Parker & DuFresne, P.A., and according to The Jacksonville Business Journal, he is an Ultimate CEO. Mr. Parker represents businesses and consumers facing bankruptcy, and homeowners in foreclosure defense actions. He is the recent recipient of Jacksonville Area Legal Aid's Award for Outstanding Pro Bono Service. Mr. Parker is an active member of the National Association of Consumer Bankruptcy Attorneys and National Association of Consumer Advocates

1/7/11

Florida Attorney General 'Fraudclosure' report...Unfair, Deceptive and Unconscionable Acts in Foreclosure Cases

Ever heard the term "All hat and no cattle?", that's basically what the AG report is...the 50 state Attorneys General task force on the issue has 'reportedly' already taken the bribe and settled with the big boys (see preceding post, below). This stuff should be the leading story of every news show.

The feeling it gives me is sort of like being in school...when the big kids cheat, then take your lunch money.
Florida Attorney General Fraudclosure Report | Unfair, Deceptive and Unconscionable Acts in Foreclosure Cases

10/26/10

How it all plays out...

Fraudclosure...Banksters...Robo-signers...and on and on.

Lots of press...lots of grandstanding politicians and Attorneys General (it is election season you know)

So SOMETHING must be done...a sacrificial lamb to calm the populace.

Bank of America...Come On Down!

I do a daily read of a very interesting financial blog, ZeroHedge. Top notch financial info and analysis. Some of these ideas were conceived there and incorporated by me, below.

This is how I think the whole foreclosure fraud/robosigning/MERS/etc will be "swept under the (Fed) rug:

BofA will go down. They are the sacrificial lamb. They will be "nationalized" and all of the trillions of dollars of garbage loans will be on the Fed books so that when the RMBS bondholders sue to get their money back, the Fed will do just that...and put these loans on their books....or maybe shift them over to Fannie and Freddie...or some new dept with a new CZAR in charge.

During the staged Govt. and Wall Street turmoil and panic, legislation will be passed to grandfather in all of the remaining robosigned/MERS recorded/missing/incorrect mortgages held by all the rest of the TBTF banks (and Fannie/Freddie). A Fed dispensation for all past fraudulent sins if you will. This new legislation will be grandfathered back to the beginning of the issuance of MBS. The panic, confusion, and complexity surrounding the change of rules and legislation will serve to obscure and direct attention away from the widespread fraud that was involved in the original creation of the individual mortgages and RMBS.

Then, people will still lose their homes. Period. Cases against the banks will be dismissed because the new laws will have been grandfathered  and absolved them of all "paperwork mistakes". Title insurers will once more be willing to write policies on foreclosed homes, and over a period of a few decades, a new department in the Fed will sell off the foreclosed homes.


And there you have it...all fixed...move along now, nothing to look at here.


10/18/10

The end does NOT justify the means!

The TBTF banks, and the mega law firms that process the foreclosure actions for them, would like you to believe that this foreclosure "mess" should really be boiled down to: "well , they didn't pay their mortgage so they shouldn't have a right to fight for or complain if they lose their house".

Just like a good magician uses misdirection to fool his audience, so are the banks and their attorneys. “‘We're not evicting people who deserve to stay in their house,’ JP Morgan Chase Chief Executive Jamie Dimon said on a conference call.” Which looks, at first glance, like a pretty fair statement. These are people who have quit paying their mortgages. They deserve what they get, and you can’t blame the banks for it...right? No, wrong.

There are laws in all 50 states that outline what a mortgage holder has to do to foreclose on a mortgage. The procedures specify what paperwork the mortgage holder has to file with the court. Because for the court to have the authority to act, it has to have evidence to act on. In a foreclosure, the paperwork is the evidence. There’s no exception in the law for skipping steps, not filing the required proof, or blatantly falsifying the documents required to show that people don’t “deserve to stay in their houses.


BOTH parties had/have certain legal obligations...BOTH parties have to fulfill those obligations...not just the borrower. There are specific laws, statutes, tax codes and UCC codes that need to be complied with by the banks/lenders/note holders....

Here is an excerpt from an email written by an individual in the financial services industry, as posted on  KeepAmericaAtWork , that concisely explains the process and  current issues: “Homeowners can only be foreclosed and evicted from their homes by the person or institution that actually has the loan paper…only the note-holder has legal standing to ask a court to foreclose and evict.

“Before mortgage-backed securities, most mortgage loans were issued by the local savings & loan. So the note usually didn’t go anywhere: it stayed in the offices of the S&L down the street.

“But once mortgage loan securitization happened, things got sloppy…as everyone knows, the loans were ‘bundled’ into REMICs (Real-Estate Mortgage Investment Conduits) and then “sliced & diced…”“…somewhere between the REMICs and MERS, the chain of title was broken.

“…what does ‘broken chain of title’ mean? Simple: when a homebuyer signs a mortgage, the key document is the note…it’s the actual IOU. In order for the mortgage note to be sold or transferred to someone else (and therefore turned into a mortgage-backed security), this document has to be physically endorsed to the next person. All of these signatures on the note are called the ‘chain of title.’

“You can endorse the note as many times as you please…but you have to have a clear chain of title right on the actual note: I sold the note to Moe, who sold it to Larry, who sold it to Curly, and all our notarized signatures are actually, physically, on the note, one after the other.

“If for whatever reason any of these signatures is skipped, then the chain of title is said to be broken. Therefore, legally, the mortgage note is no longer valid. That is, the person who took out the mortgage loan to pay for the house no longer owes the loan, because he no longer knows whom to pay.

“The broken chain of title might not have been an issue if there hadn’t been an unusual number of foreclosures. Before the housing bubble collapse, the people who defaulted on their mortgages wouldn’t have bothered to check to see that the paperwork was in order.

“But …following the housing collapse of 2007-’10-and-counting, there has been a boatload of foreclosures…and foreclosures on a lot of people who weren’t sloppy bums who skipped out on their mortgage payments, but smart and cautious people who got squeezed by circumstances.

“These people started contesting their foreclosures and evictions, and so started looking into the chain-of-title issue, and that’s when the paperwork became important. So the chain of title became crucial and the botched paperwork became a nontrivial issue.

“…the banks had hired ‘foreclosure mills’…law firms that specialized in foreclosures…in order to handle the massive volume of foreclosures and evictions that occurred because of the housing crisis. The foreclosure mills …were the first to spot the broken chain of titles.

“…it turns out that these foreclosure mills might have faked and falsified documentation, so as to fraudulently repair the chain-of-title issue, thereby ‘proving’ that the banks had judicial standing to foreclose on delinquent mortgages. These foreclosure mills might have even forged the loan note itself…

The foreclosure mills did actually, deliberately, and categorically fake and falsify documents, in order to expedite these foreclosures and evictions.

I, myself, have seen a price list for these ‘services’ from a company called DocX…yes, a price list for forged documents. Still, the banks and foreclosure mill firms would like you to believe that "the end justifys the means".

A USA Today piece, ("Foreclousre processors say they didn't review much") about the "robo-signer" component to the fruad reveals that the banks literally hired people off the street, gave them an impressive title, (and a pen), and had them sign thousands of documents and affidavits a month without reviewing or even knowing the terminology contained in the documents.

I, myself, have seen a price list for these ‘services’ from a company called DocX…yes, a price list for forged documents. Still, the banks and foreclosure mill firms would like you to believe that "the end justifys the means".

Now all of this doesn't mean that everyone should get a home for free...but the banks need to LEGALLY go through the foreclosure process, THAT'S what this is about...


10/15/10

Foreclosures Gone Wild...Chapter 2

In the previous FGW post (below), I explained a bit about 1 aspect of the foreclosure mess, MERS. Here, I'll discuss the next problem in the process...Title Insurance.

First, here is a brief explanation of what title insurance is: It provides coverage for future claims or future losses due to title defects which are created by some past event (i.e., event prior to the acquisition of the property.) Protecting purchasers against loss is accomplished by the issuance of a title insurance policy, which states that if the status of the title to a parcel of real property is other than as represented, and if the insured suffers a loss as a result of title defect, the insurer will reimburse the insured for that loss and any related legal expenses, up to the face amount of the policy.


A few headlines out this week:
  • Old Republic National Title Insurance, the fourth-largest title insurer in the country, announced it will not write new policies for foreclosed homes handled by the four major institutions that disclosed possible paperwork improprieties
  • The Federal Housing Administration Commissioner, David Stevens, has joined David Axelrod in stating that the Administration sees no reason to halt all foreclosures...“We believe freezing foreclosures for all banks in all states, whether we have reason to believe them to be in error or not,(can you believe that he actually said that out loud, in public!) is simply not the prudent step to take in this fragile housing market,” he said.
It should be crystal clear to everyone exactly who the administration is trying to protect here...they talk about protecting the homeowners and the fragile housing market, but they are just protecting the TBTF  (too big to fail) banksters. Just keep on pushing forward...federal and state laws/statutes be damned! How about the next time the IRS calls you in for an audit regarding all of that under reported tax liability, just tell them that it was a 'clerical' error that they shouldn't worry about.

To get back to the title insurance issue...if we look back at the past 24 months of issued policies, are we going to be seeing huge claims against the Title Insurers who issued policies on all of the foreclosures already sold? Are we going to see new policies issued (if, in fact the insurers issue policies on foreclosures going forward) with specific exceptions built in to shield the insurers? Is the price of title insurance going to jump, or is there going to be a new Govt. title insurer of last resort (funded by the good old American taxpayer)  like what happened in the Florida homeowner insurance market? Or, as I have been hearing for the past few days, are the TBTF banks going to reach an "understanding." with the title insurers that if they suffer claims losses as a result of faulty paperwork (FRAUD), the banks will pick up the tab? If this last scenario happens, it will, in my humble opinion, just become another taxpayer pass-thru directly to the TBTF institutions from the untraceable TARP funds.

Take my word for it...shortly (but possibly after the midterm elections) you will hear about (or maybe it will be hardly reported at all) a Title insurance loss 'backstop' plan...it may even look like it is coming from the banks...but it's coming from me, you and the rest of the flock.

But every cloud has a silver lining...right? The silver lining that I see here is twofold:
  1. Maybe the banks will get serious, trained, and organized regarding the processing of short sales. If, in order to take back a foreclosure, they are going to have to accurately identify ownership and complete legally verifiable paperwork, they may think that it is easier and more profitable to just approve a short sale.
  2. The homes of all of our clients that are traditional sales should look that much more attractive to the buyers out there now...allowing those values/prices to firm up.
Thanks for reading...and come back for the next installment of ...Foreclosures Gone Wild!

10/13/10

Foreclosures Gone Wild!

Let me explain a little bit about this MERS problem...

Unless you have three kids under the age of 4, watch only the Sprout channel and have no time to read the paper, you have heard about the foreclosure paperwork mess (otherwise known as FRAUD).

An acronym being tossed around in these reports, MERS, is a (pseudo) company at the center of one of the main issues

MORTGAGE ELECTRONIC REGISTRATION SYSTEMS INC...the actual name of the business entity. MERS is a Delaware corporation whose sole shareholder is Mers Corp. MersCorp and its specified members (the Lending Institutions) have agreed to include the MERS corporate name on any mortgage that was executed in conjunction with any mortgage loan made by any member of MersCorp. (UPDATE 9/1/2010: 65 MILLION American Mortgages).

MERS is a shell corporation with no employees, but thousands of officers

In the mid-1990s mortgage bankers decided they did not want to pay recording fees for assigning mortgages anymore. This decision was driven by securitization—a process of pooling many mortgages into a trust and selling income from the trust to investors on Wall Street. Securitization, also sometimes called structured finance, usually required several successive mortgage assignments to different companies. To avoid paying county recording fees, mortgage bankers formed a plan to create one shell company that would pretend to own all the mortgages in the country—that way, the mortgage bankers would never have to record assignments since the same company would always “own” all the mortgages.

From the site StopForeclosureFraud.com comes the following: Thus in place of the original lender being named as the mortgagee on the mortgage that is supposed to secure their loan,MERS is named as the “nominee” for the lender who actually loaned the money to the borrower. In other words MERS is really nothing more than a name that is used on the mortgage instrument in place of the actual lender. MERS’ primary function, therefore, is to act as a document custodian.

MERS was created solely to simplify the process of transferring mortgages by avoiding the need to re-record liens – and pay county recorder filing fees – each time a loan is assigned. Instead, servicer’s record loans only once and MERS’ electronic system monitors transfers and facilitates the trading of notes. It has very conservatively estimated that as of February, 2010, over half of all new residential mortgage loans in the United States are registered with MERS and recorded in county recording offices in MERS’ name.

MersCorp was created in the early 1990’s by the former C.E.O.’s of Fannie Mae, Freddie Mac, Indy Mac, Countrywide, Stewart Title Insurance and the American Land Title Association. The executives of these companies lined their pockets with billions of dollars of unearned bonuses and free stock by creating so-called mortgage backed securities using bogus mortgage loans to unqualified borrowers thereby creating a huge false demand for residential homes and thereby falsely inflating the value of those homes...

The MERS paperless system is the type of crooked rip-off scheme that is has been seen for generations past in the crooked financial world. In this present case, MERS was created in the boardrooms of the most powerful and controlling members of the American financial institutions. This gigantic scheme completely ignored long standing law of commerce relating to mortgage lending and did so for its own personal gain.

The American media routinely identifies MERS as a mortgage lender, creditor, and mortgage company, when in point of fact MERS has never loaned so much as a dollar to anyone, is not a creditor and is not a mortgage company. MERS is merely a name that is printed on mortgages, purporting to give MERS some sort of legal status, in the matter of a loan made by a completely different and almost always,a totally unknown entity.

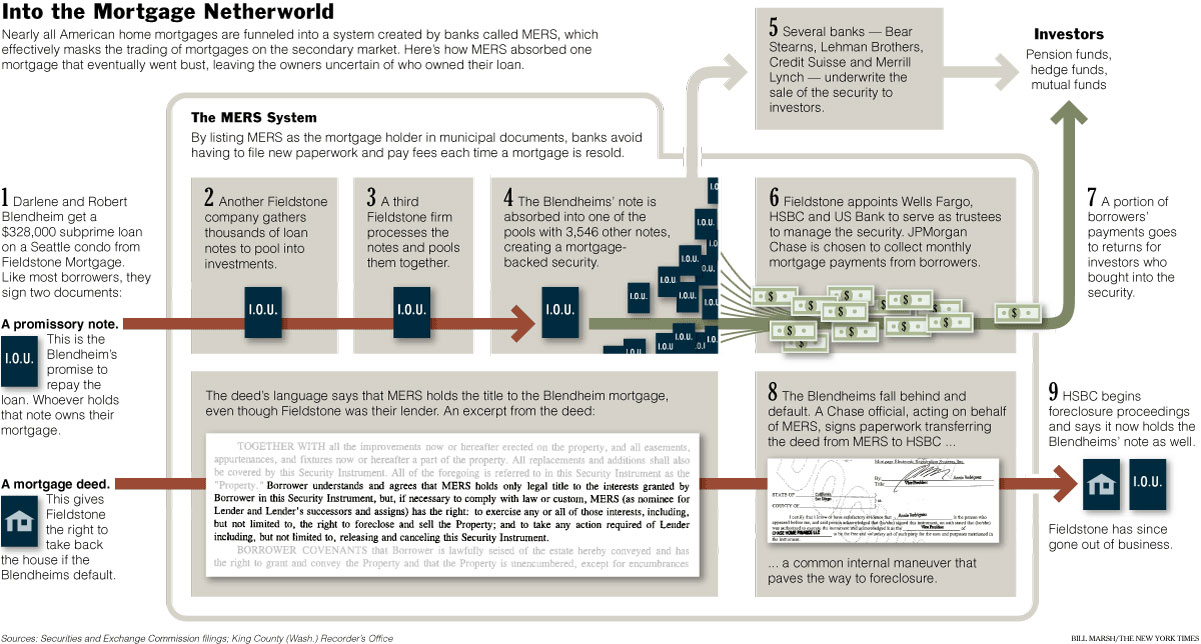
Here is a graphic that concisely explains the scam...er, I mean process:


Now here is the big SCAM component of MERS (taken from a  Law Review paper written by Professor Christopher Lewis Peterson, Univ of Utah): To accommodate the massive amount of paperwork and litigation involved with its business model, MERSCORP simply farms out the MERS, Inc. identity to employees of mortgage servicers, originators, debt collectors, and foreclosure law firms...MERS invites financial companies to enter names of their own employees into a MERS webpage which then automatically regurgitates boilerplate “corporate resolutions” that purport to name the employees of other companies as “certifying officers” of MERS. These certifying officers also take job titles from MERS stylizing themselves as either assistant secretaries or vice presidents of the MERS, rather than the company that actually employs them. These employees of the servicers, debt collectors, and law firms sign documents pretending to be vice presidents or assistant secretaries of MERS, Inc. even though neither MERSCORP, Inc. nor MERS, Inc. pays any compensation or provides benefits to them. Astonishingly, MERS “vice presidents” are simply paralegals, customer service representatives, and foreclosure attorneys employed by other companies. MERS even sells its corporate seal to non-employees on its internet web page for $25.00 each. Ironically, MERS, Inc.—a company that pretends to own 60% of the nation’s residential mortgages—does not have any of its own employees but still purports to have “thousands” of assistant secretaries and vice presidents...

I won't go into any further sordid details here, as you'd probably fall asleep. But I wanted to start this series of posts with this brief explanation of one of the main players in the "Foreclosures Gone Wild" game.  Stay tuned for ...the rest of the story.


Real Time Web Analytics